Secure login and onboarding
Biometric login, passkeys, and device binding, plus an onboarding flow that hands identity checks to your KYC provider.

For banks, credit unions, and fintechs: an app your customers trust, built on your core or BaaS APIs and published under your own name. From $1,400.
2X
More customers banking on mobile
100%
Logins protected by MFA
Teams we have built for:














The Problem
The gap shows when customers compare your app with the fintech app on the same phone. Logins fail, simple tasks need a branch call, and every release waits on a vendor's roadmap.
Login loops
Customers get locked out when the app forgets their device.
Login loops
Biometric login with device binding keeps trusted phones signed in, with MFA for new ones.
Card controls
Freezing a lost card still takes a phone call.
Card controls
Freeze, unfreeze, and limit controls call your card processor's API from inside the app.
Vendor roadmap
Feature requests wait in a white-label vendor's queue.
Vendor roadmap
You own the code, so your team sets the release order.
Risky transfers
New payees and large transfers go through with one tap.
Risky transfers
Step-up checks ask for a fresh biometric or code before money leaves.
It's payday Friday and your support line is full. A member can't log in because the app forgot her phone again. Another wants to freeze a lost card, but that screen doesn't exist, so he calls. Your white-label app follows the vendor's release notes, not your roadmap, and one feature request takes two quarters. Customers don't leave over one bad login. They leave when the fintech app on the same phone does everything yours makes them call about.
We start from the APIs you already have: your core banking system, BaaS partner, or card processor. Then we build the app layer on top: biometric login with device binding, account views, transfers with step-up checks, card controls, statements, and alerts. Security follows the OWASP MASVS from the first sprint. The app ships under your own developer accounts, so your roadmap stops depending on a vendor's release calendar.
Biometric login with MFA
Face ID, fingerprint, or a passkey signs customers in, and new devices prove themselves with a second factor.
Card controls in the app
Customers freeze, unfreeze, and limit their own cards through your card processor's API.
Your code, your roadmap
The app and its developer accounts belong to you, so releases follow your priorities.
Our Banking App Development Process
You see the API map and the security plan before design starts, click through every screen before code, and approve each test build on your own phone.
We read your core, BaaS, or card processor API docs and list what the app can do on day one. You get a feature map, your provider's gaps, and a written scope.
What's Included
Your build covers login and onboarding, accounts and transactions, transfers, card controls, statements, and alerts, connected to your core or BaaS APIs and tested against mobile security controls.
Compare Options
A white-label app gets you live fast, and an in-house team suits banks with years of mobile work ahead. Here is where each fits, and where a custom build makes more sense.
| Feature | DeveloperLookBest fit | White-label app | In-house team |
|---|---|---|---|
| Time to first release | 8 to 22 weeks | Weeks once contracted | 6 to 12 months to hire |
| Brand and design | Fully your design | Your logo on their template | Fully your design |
| Feature roadmap | You set the order | Vendor sets the order | You set the order |
| Core and BaaS fit | Built on your APIs | Their supported cores only | Built on your APIs |
| Security testing | MASVS checks every release | Vendor's own testing | Depends on your hires |
| Upfront cost | Fixed price per release | Lower setup cost | Salaries before first release |
| Ongoing fees | No license fees | License fee per user or year | Payroll and tools |
| Code ownership | You own the code | Vendor owns the code | You own the code |
Projects We've Built
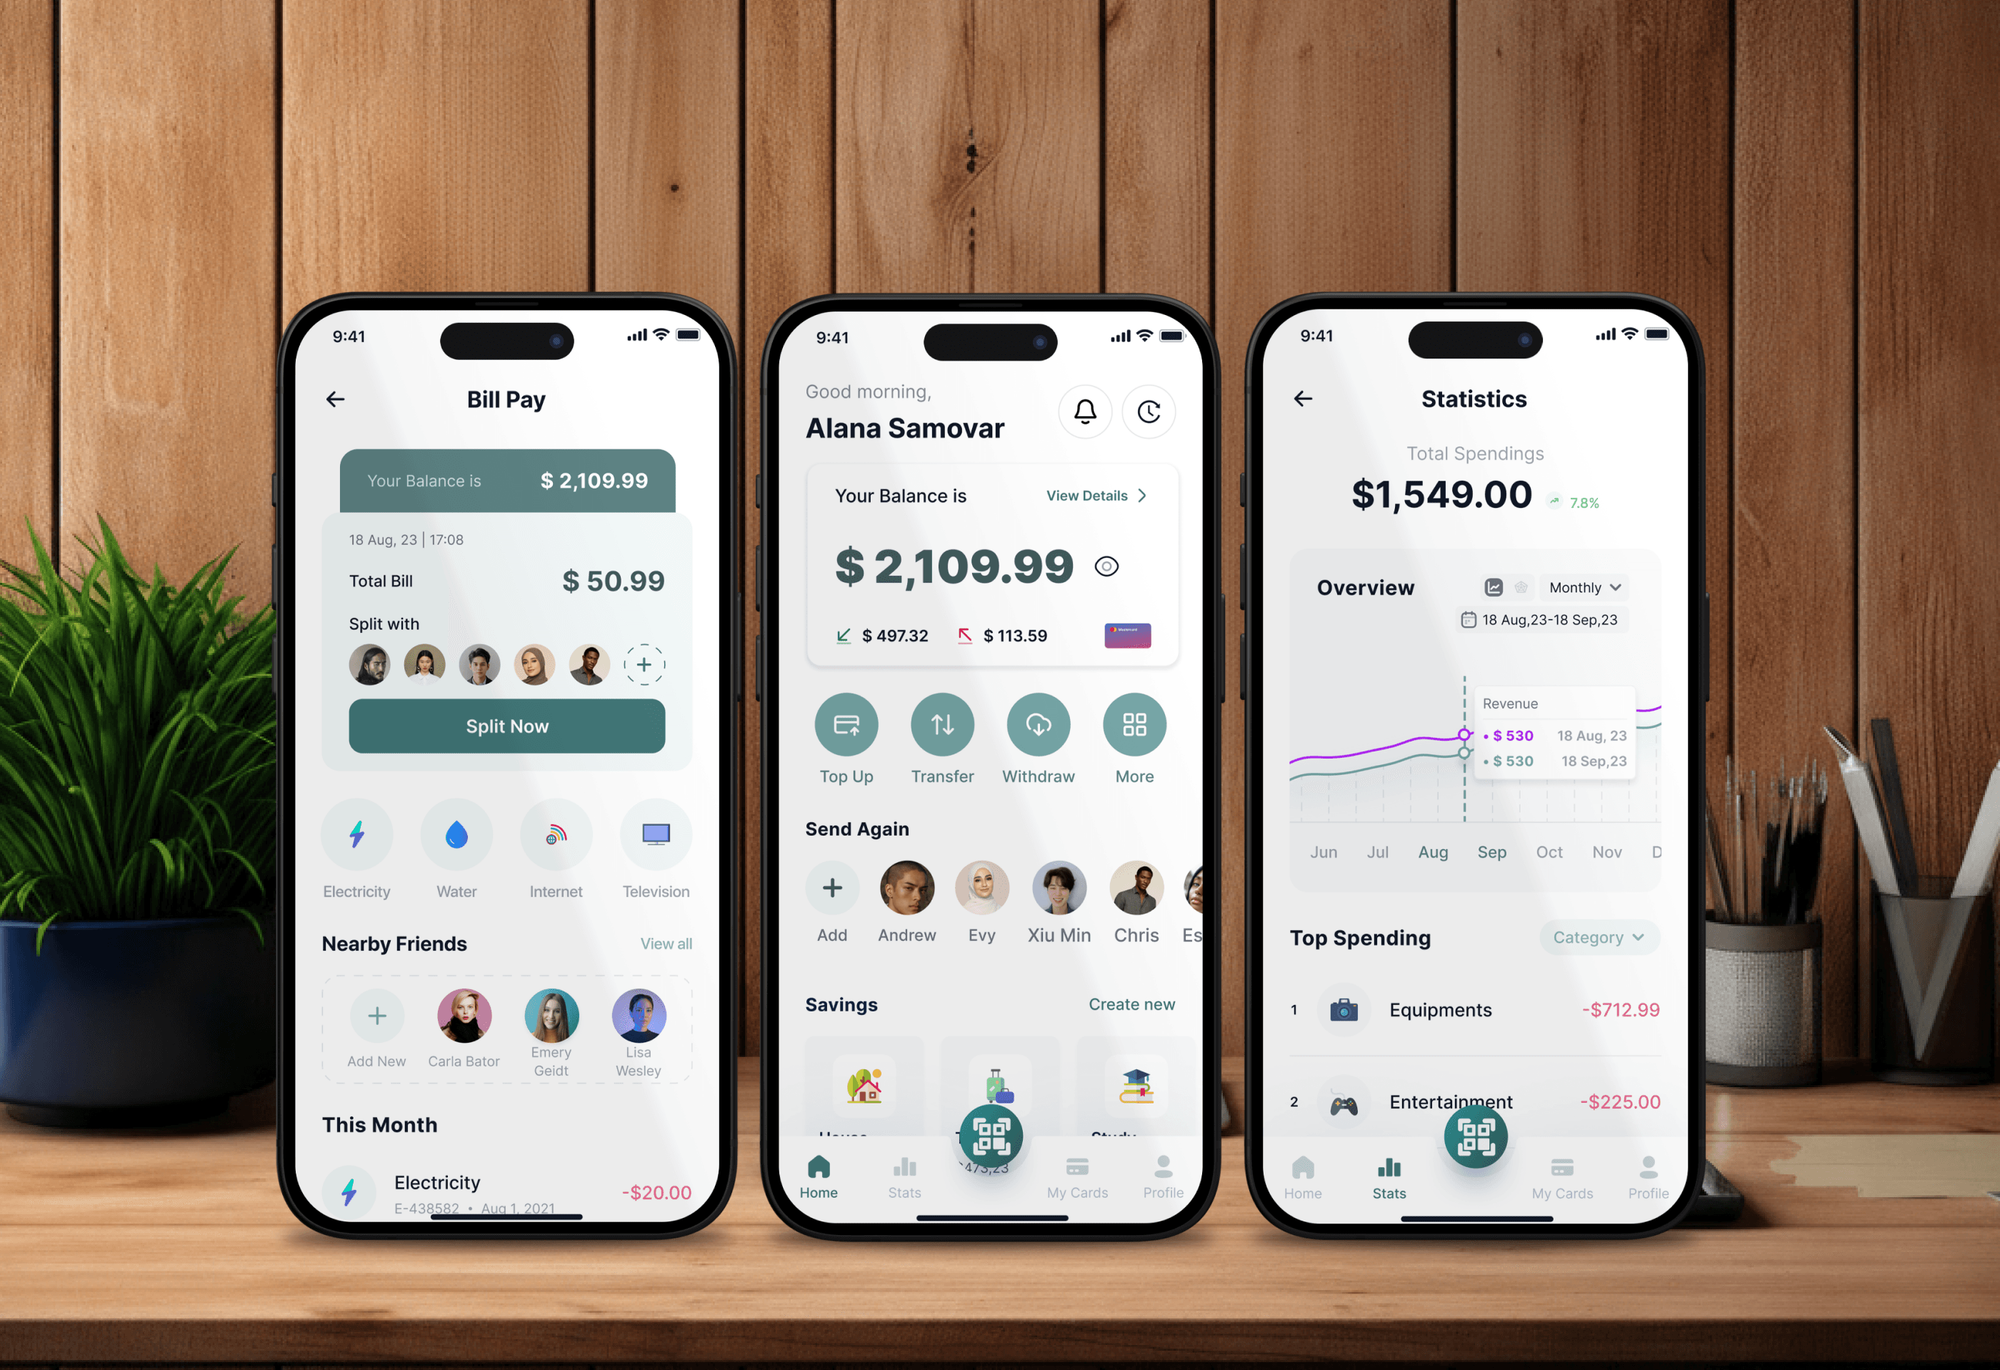
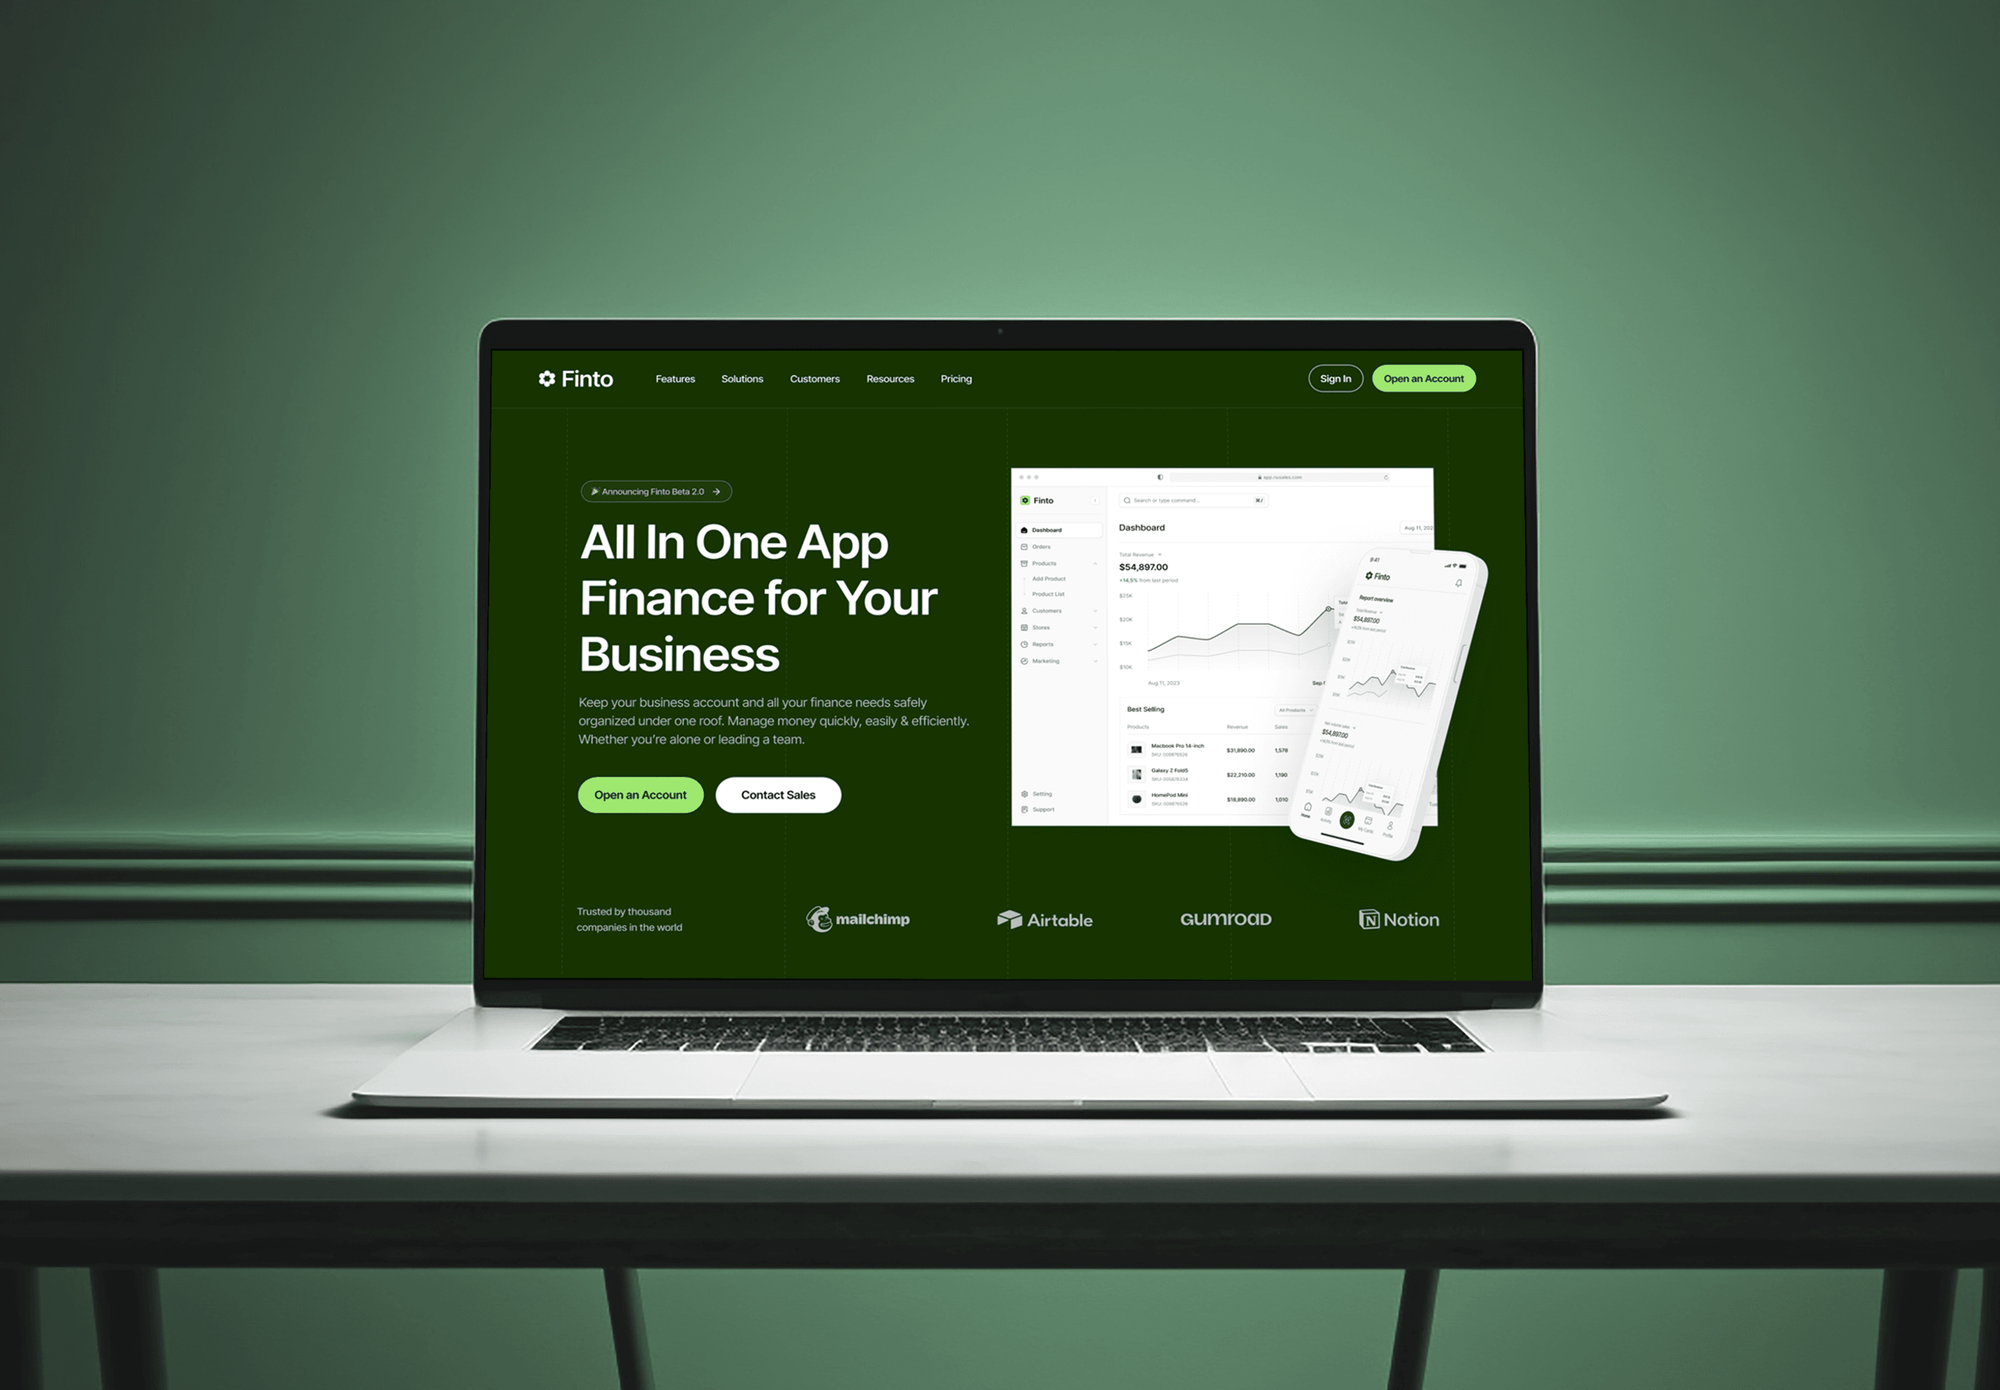
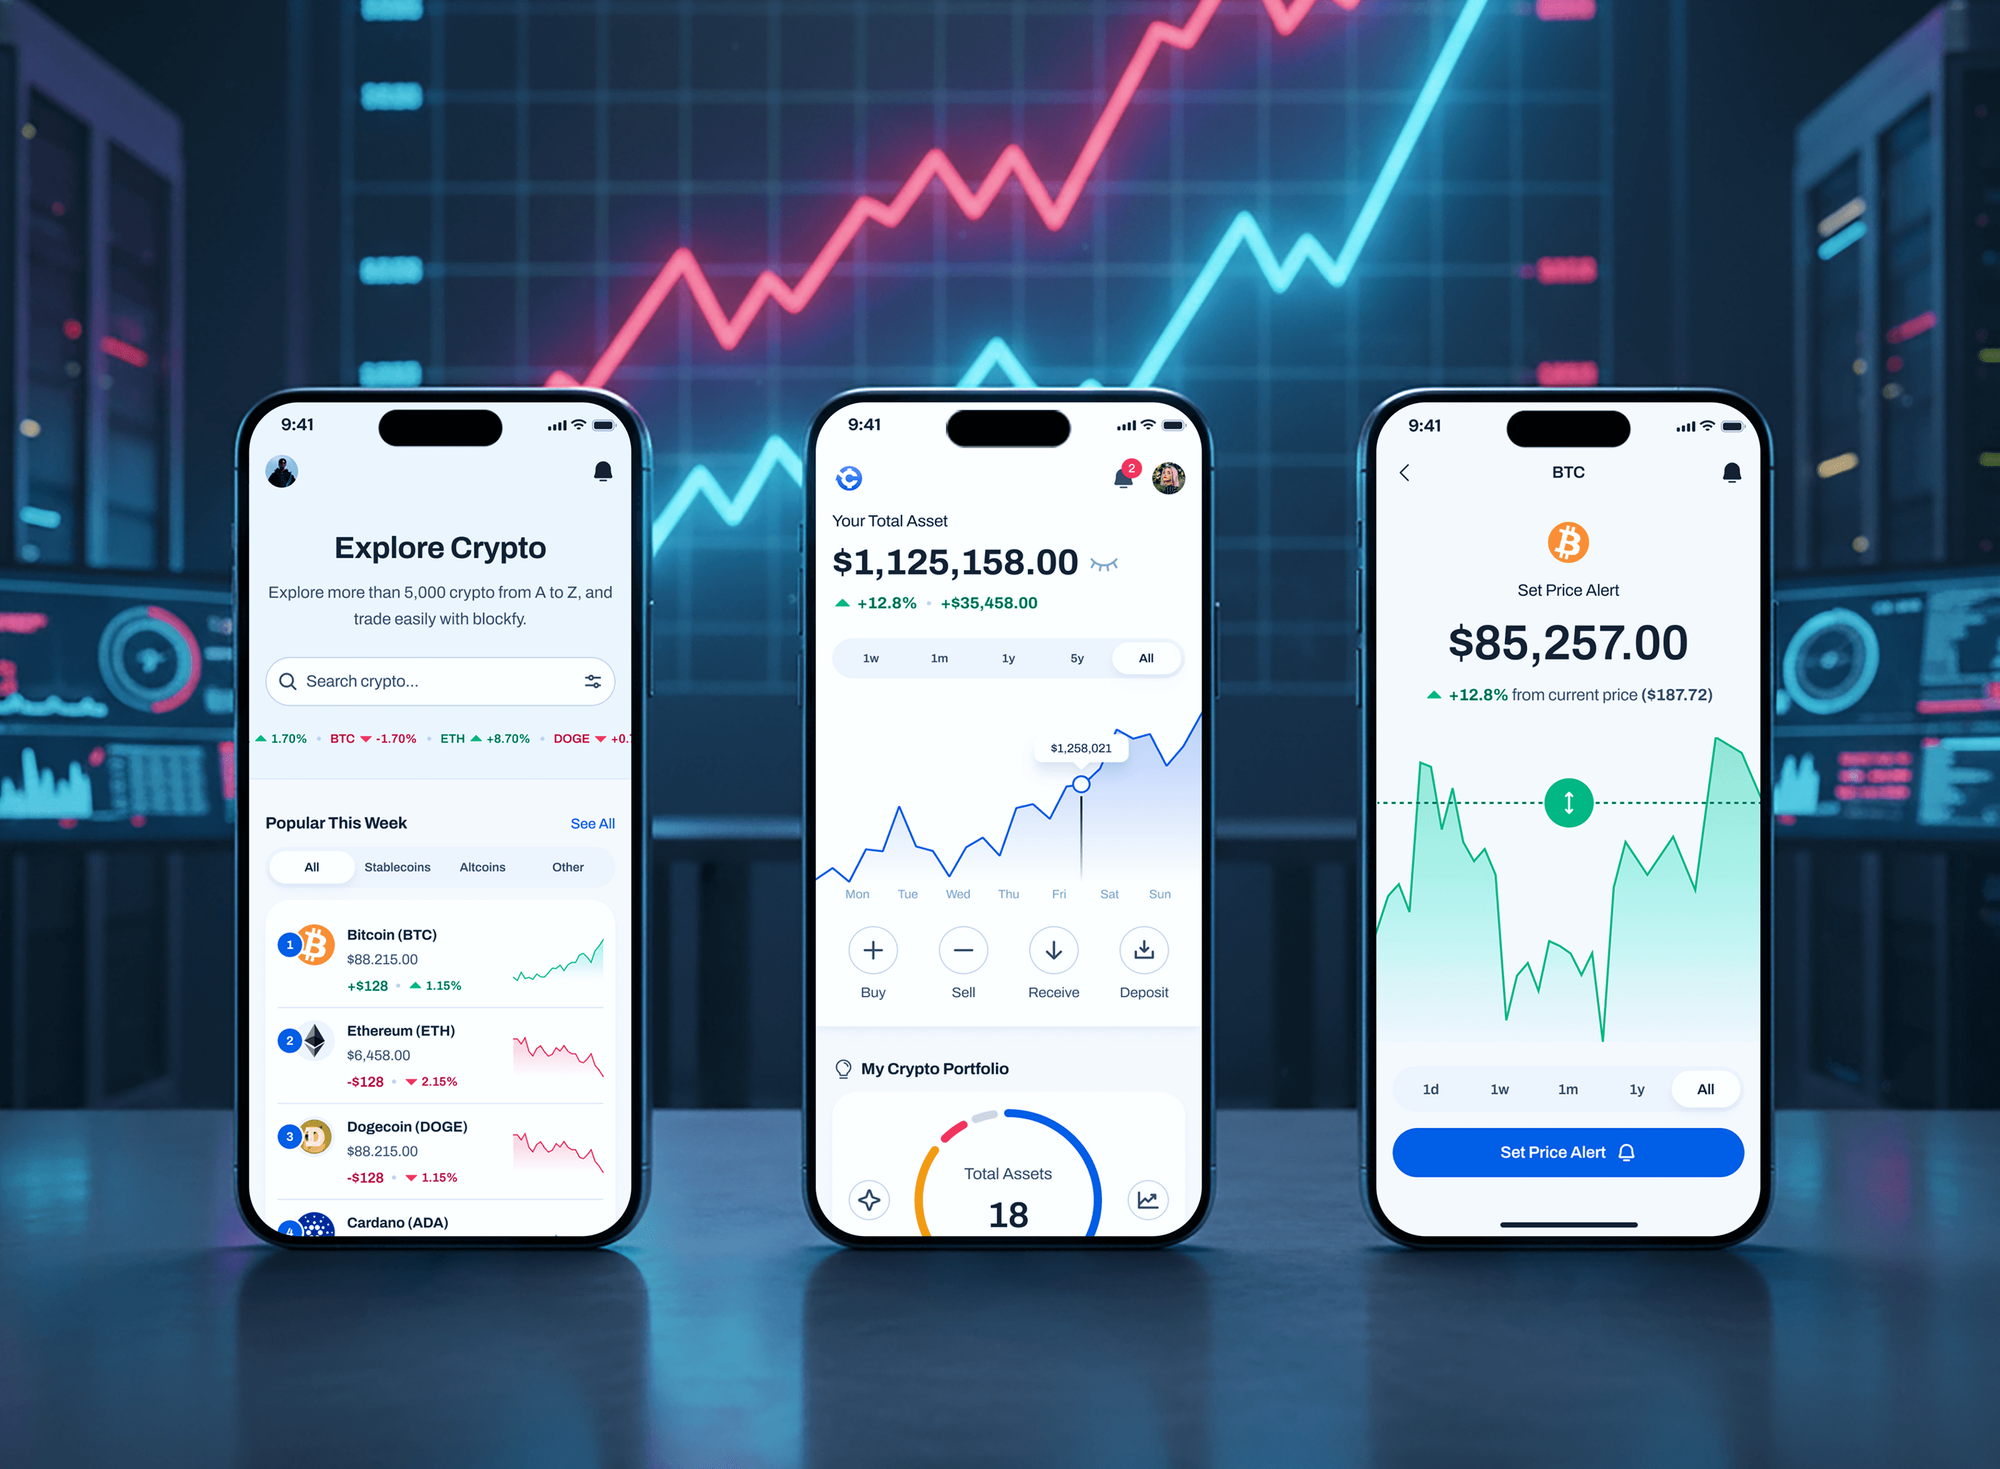
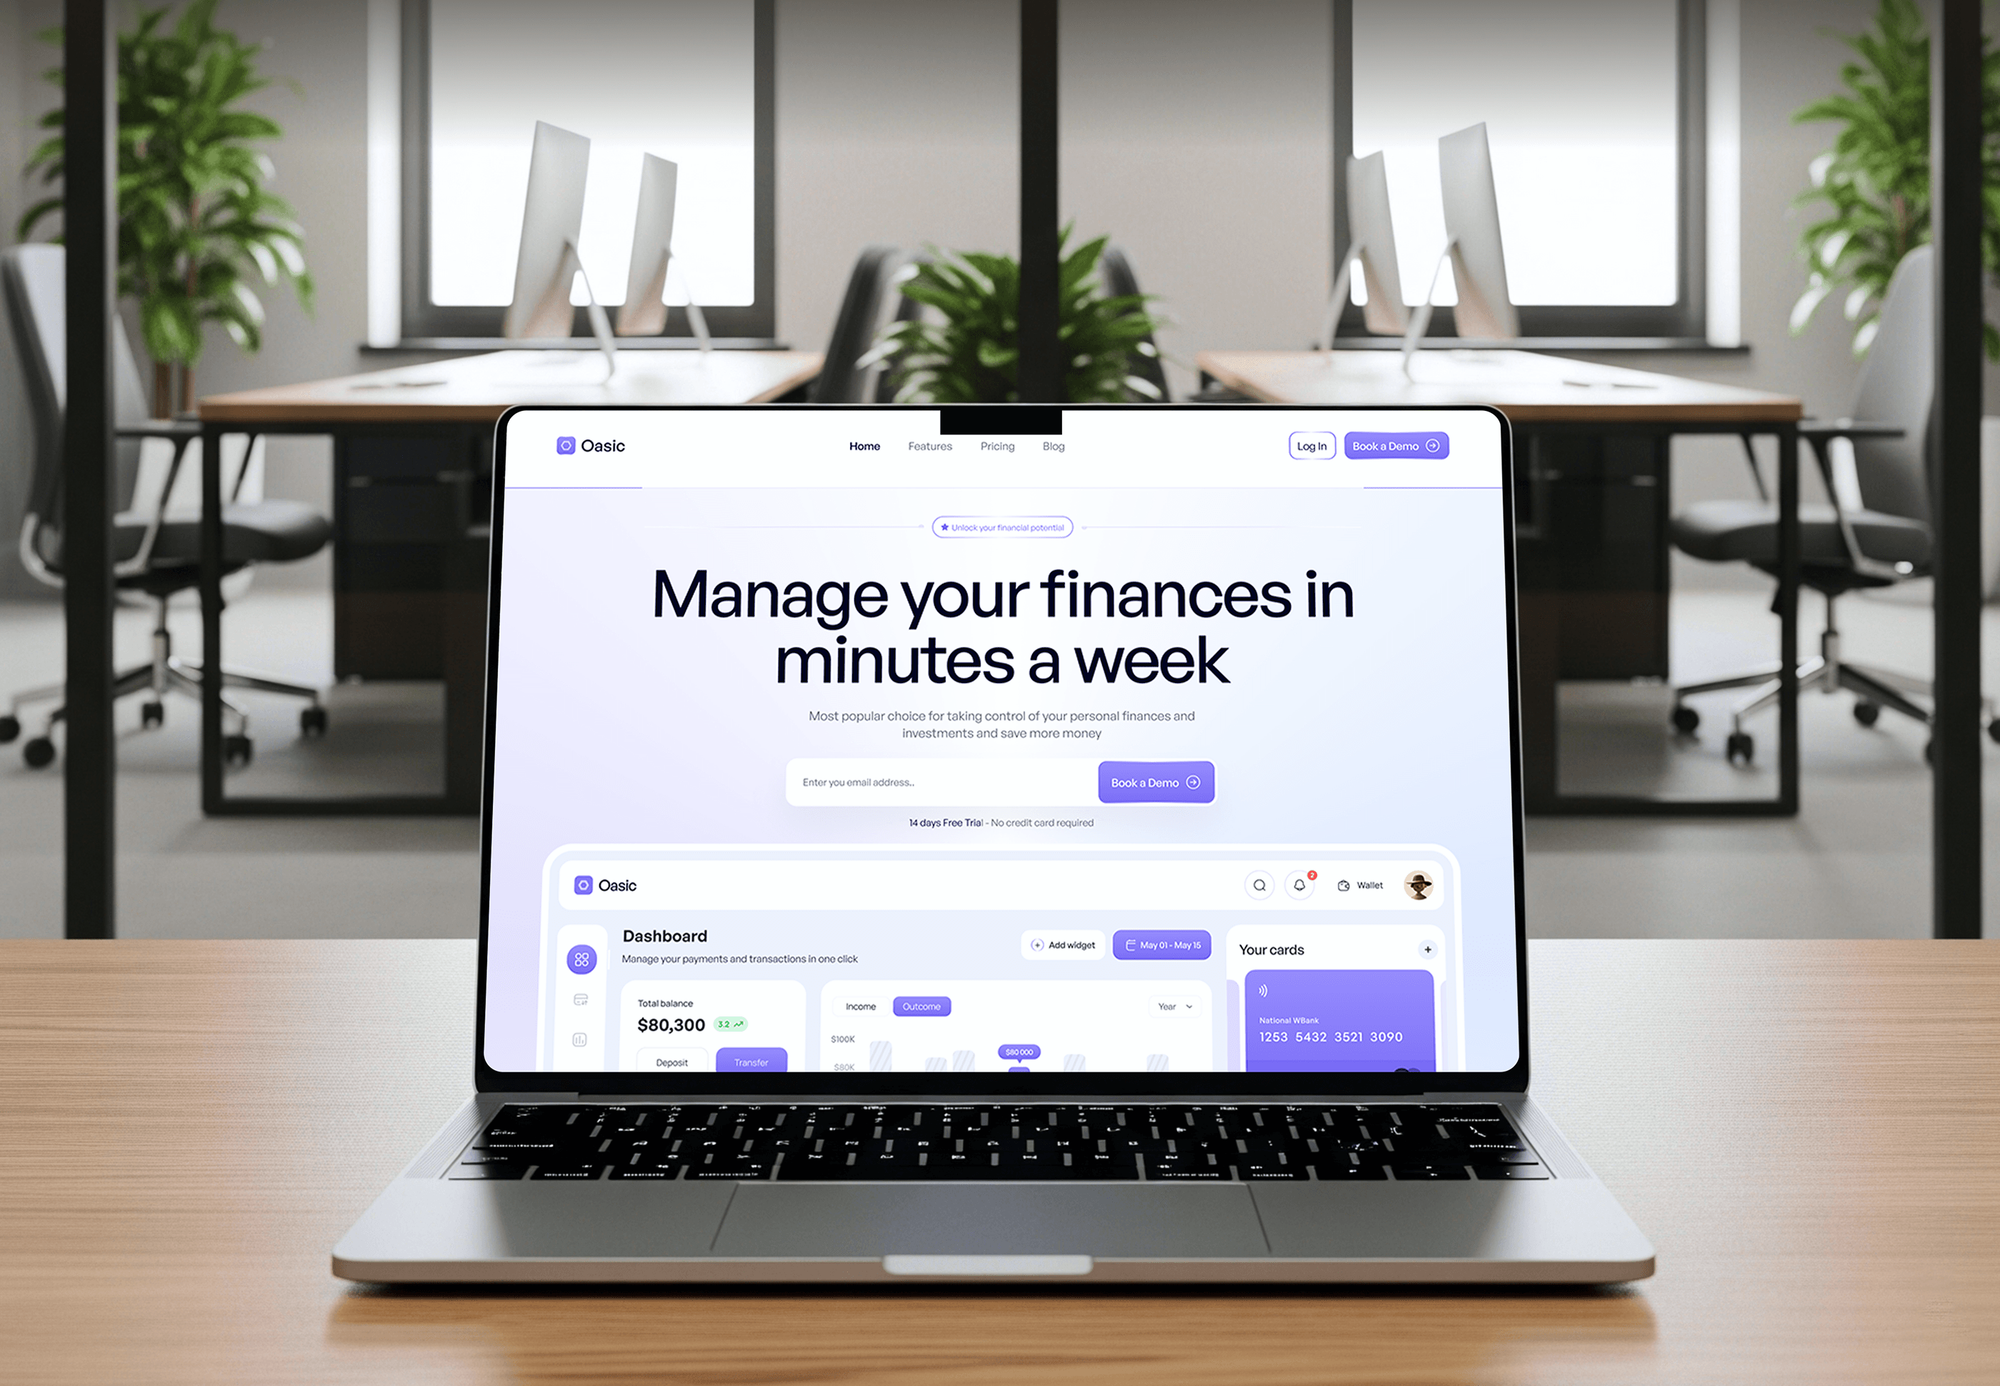
Moneywish, Finto, CoinSphere, and Oasic are finance products we designed and built, with balances, transfers, cards, and dashboards. They are fintech builds, not apps for a chartered bank.
What Our Clients Say
Feedback from teams we have built finance apps, dashboards, and web products for.
We had a pretty specific idea of what we wanted our website to become, but I wasn’t sure how easily we could explain all of it to a development team. There were quite a few moving parts, and we were working toward a deadline, so I expected a few things to get lost along the way. That never really happened. They understood what we were trying to achieve, kept us updated throughout the process, and got everything ready within the agreed timeline. The final site feels much easier to navigate, works beautifully on mobile, and is noticeably smoother for our customers. It was a huge relief seeing the original idea actually turn into the website we had in mind.
The mobile experience is probably my favourite part of the new site. We had spent a lot of time making sure the desktop version looked right, and the team kept pushing us to think about how everything would actually feel on a phone too. They were right. The navigation is clean, the interactions feel natural, and everything we’ve tested so far works exactly as it should. They also went through the links, forms, integrations, and other details more than once before launch, which I really appreciated. And even after going live, we could still reach out when something came up. The whole process felt friendly, organised, and surprisingly straightforward.
What I appreciate most is that the website is actually easy for us to manage now. We can update content ourselves instead of sending a developer a message every time we need to change something small. They also paid attention to the technical SEO side, which mattered to us because we didn’t want a new website to create problems for the traffic we already had. I’ve probably asked more questions than I should have since launch, but every question has been handled patiently and without any fuss. The team is easy to work with, they explain things clearly, and when we need something changed, they focus on getting it done rather than making the process complicated.
1,250+
Projects shipped
10+
Years of experience
Top 3%
Upwork Top Rated Plus
5 stars
Average review score
1,250+
Projects shipped
10+
Years of experience
Top 3%
Upwork Top Rated Plus
5 stars
Average review score

Want results like these?
Tell us what you are building. You get a reply within 24 hours on business days, then a written estimate.
Work Culture
Your app holds customers' money and personal data, and both regulators and app reviewers look closely. These habits keep your build safe to ship and easy to audit.
We run OWASP MASVS checks during the build, not only in a final audit. Tokens in plain storage get fixed while the code is fresh.
We build the controls your compliance team asks for and document how each one works. Legal and regulatory sign-off stays with your team and your sponsor bank.
Every release ships with test results, a third-party SDK list, and data flow notes. Your vendor management and audit teams get what they need without chasing us.
We test on older iPhones and mid-range Android phones with screen readers and large text on. Your oldest customers get an app that still works for them.
If your core provider's white-label app covers your needs, you'll hear that on the first call. We quote a custom build only when it pays off.
Both apps publish under your Apple and Google developer accounts. The code, signing keys, and build pipeline stay yours if you ever change developers.
Overview
DeveloperLook is a banking app development company for banks, credit unions, and fintechs. We build iOS and Android apps with biometric login, account views, transfers, card controls, and alerts on top of your core or BaaS APIs. Projects start at $1,400, take 8 to 22 weeks, and every release is tested against the OWASP MASVS before it ships.
DEVELOPERLOOK
Project facts · Banking App Development Company
Reviewed 28 Oct 2026 by Saimul Islam
Good fit
Community banks replacing a white-label app
Your core provider's white-label app gets one-star reviews, and you want an app of your own that runs on the same core APIs.
Credit unions adding digital card controls
Your members call to freeze lost cards and ask about charges, and you want those tasks in the app, connected to your card processor.
Fintechs launching on a BaaS partner
You're launching a digital account on a banking-as-a-service partner and need iOS and Android apps built on its APIs and sandbox.
Product leads planning a Revolut-style app
Your board wants an app like Revolut, and you need someone to say which features to launch first and which to leave for later.
Agencies with a banking client
Your agency won a credit union redesign, and the client now wants mobile banking app developers who have shipped finance apps before.
Not a fit
Loan origination software
You need a system that takes loan applications, runs decision rules, and services payments. Our Lending Software Development page covers that build.
Payments product, not banking
You're building a wallet, P2P transfers, or a card payment app without bank accounts behind it. Our Payment App Development page fits that scope better.
Website redesign only
You need a new public website for your bank or credit union, not a mobile app. Our Bank and Credit Union Website Design page covers that.
Budget under $1,400
Your budget is under $1,400, or your core provider's white-label app already does what you need. If it does, we'll tell you before we quote.
Not sure we're the right fit?
Book a free call or message us. We'll tell you honestly whether we're the right team.
Pricing
These are starting points in USD. Your final price depends on your provider's API, the platforms you need, and testing depth. You get a fixed proposal after a free API review.
For Agencies
You own the client relationship. We supply the mobile and security engineering for the apps your bank and credit union clients give their members. We build under your brand and document everything for vendor review.
White label: your client only ever sees your brand
Send the client's core provider, features, and deadlines, and we shape the scope together.
You get a fixed proposal in your agency's name and a named team.
We build, test against MASVS, and hand over code and store access.
Send the client's core provider, features, and deadlines, and we shape the scope together.
You get a fixed proposal in your agency's name and a named team.
We build, test against MASVS, and hand over code and store access.
The Right Technology for Your Project
We build native or cross-platform apps with proven mobile tools, connect them to your provider's APIs, and test them with standard mobile security tooling.
 React Native
 Flutter
 Node.js
 PostgreSQL
 AWS
 Docker
 OWASP MASVS
 Firebase Crashlytics
Related Services
Lending, payment, and identity verification builds for the same app, plus Plaid bank linking, fintech security reviews, and our wider mobile app team.
This page
Banking App Development Company
Pairs with the 6 services around it
FAQ
Straight answers on cost, timelines, security, app store rules, core and BaaS connections, and ownership.
Saimul IslamFounder & CEO, DeveloperLookStill have questions?
Send a message or book a call with the team.
A banking app from DeveloperLook starts at $1,400 for a companion app on your existing core API, with biometric login, balances, statements, and alerts. Transfers, card controls, and bill pay start at $4,600. A digital bank launch with account opening, KYC checks, and virtual cards starts at $9,400. You get a fixed quote after a free API review.
A DeveloperLook build takes 8 to 22 weeks, depending on features and how complete your provider's API is. A companion app takes about 8 to 10 weeks. Transfers and card controls push it to 14 to 18 weeks, and a digital bank launch to about 22. A missing endpoint on your provider's side is the most common delay.
You develop a mobile banking app by starting from your provider's API, not the screens. First list what your core, BaaS partner, or card processor exposes. Then design, build in sprints against the sandbox, test against the OWASP MASVS, and submit under your own developer accounts. Teams that start with screens design features the API can't support.
Yes, we can build on your existing core if it exposes APIs for accounts, transactions, and transfers. Many cores offer a digital banking API or an integration partner. If yours doesn't, we add a small backend between the app and the core. Core credentials then stay on your servers instead of customers' phones.
You build a Revolut-style app one market and one product at a time. Revolut started with a card and currency exchange, then added trading and more over years, with licenses in each market. A first release usually pairs a BaaS partner's accounts and cards with a polished app: onboarding, balances, transfers, and card controls. Exchange and investing come later, each with its own licensing questions.
The development team handles the build: secure code, the controls your team specifies, testing, and documentation. Your compliance team and sponsor bank decide the rules, such as disclosures, KYC thresholds, and screen wording. We turn their decisions into features and give them test evidence for each control. Regulatory sign-off stays with your institution.
Security comes from building to a checklist such as the OWASP MASVS and testing against it before every release. That means tokens in the iOS Keychain or Android Keystore, certificate pinning, session timeouts, and jailbreak or root checks. Android balance screens block screenshots, and iOS screens hide during screen recording. Adding a payee asks for a second factor.
Both app stores expect banking apps to come from the institution itself. Apple's App Review Guideline 5.1.1(ix) says apps in highly regulated fields, banking included, should be submitted by the legal entity that provides the service. Google Play asks financial services developers to register as an organization and complete its financial features declaration. We prepare reviewer logins too.
Choose cross-platform for most projects, and native when you need deep platform features. React Native or Flutter share one codebase across iOS and Android, which keeps cost and release timing aligned. Swift and Kotlin suit apps that lean on Apple Pay provisioning, widgets, or device security APIs. We recommend one after the API review.
You own the app code, the backend, and the app store listings. Both apps publish under your institution's Apple and Google developer accounts, which the stores expect for banks anyway. At launch we hand over the repository, build pipeline, and runbooks. Then you get 60 days of post-launch support for bugs, store feedback, and small changes.
Saimul IslamFounder & CEO, DeveloperLookStill have questions?
Send a message or book a call with the team.
Free 30-min callGoogle Meet
Book a call
In 30 minutes on Google Meet we walk you through how we would build it, how long it takes and what it costs. Then you get a written estimate.
Calendar not showing? Book on cal.com or send a brief.